
buying property in spain
Three Spanish Property Myths That Can Cost You Money

A model house sits on the Spanish flag. Photo: Mehaniq / Shutterstock
When buying property in Spain, you are often told to “check the paperwork!” That is good advice, but the problem is that many people assume that one particular document, or one particular professional, gives them a complete guarantee that everything is in order.
It doesn’t.
Hopefully, if you are buying a property, you are taking proper professional advice and not relying entirely on Bob at the bar, who bought a house in Spain twenty years ago and has been giving property advice ever since.
That said, even those who are trying to do things properly can fall into some common traps…
Here are three of the misconceptions I come across most often:
Myth 1: “The Nota Simple is in order, so the property must be legal.”
A Nota Simple from the Land Registry is an extremely important document. It shows the registered description of the property, who owns it and whether there are registered mortgages, embargoes or other rights affecting it.
But it is not a planning certificate and it does not, by itself, confirm that every extension, swimming pool, garage or outbuilding has the necessary planning permission or lawful planning status.
Think of the Nota Simple as an informative summary of the property’s registered legal position.
Myth 2: “It appears on the Catastro, so it must be legal.”
Another common misconception. The Catastro is an administrative register which records the physical, economic and legal characteristics of property for cadastral purposes.
A construction appearing there does not prove that the Town Hall authorised it or that it complies with planning laws.
Myth 3: “We signed at the notary, so everything must be fine.”
The notary performs an essential role in a Spanish property sale. They verify the identity and capacity of the parties, review ownership and registered charges, check cadastral and certain tax-related information, and ensure that the deed complies with the legal requirements for the transaction.
But the notary does not physically inspect the property or certify that every structure on the land complies with planning law.
The reality is that no single document tells you everything about a Spanish property.
A safe purchase means comparing the Land Registry, Catastro, planning position and the physical reality of the property, and investigating any differences before you commit.
Buying property in Spain should be exciting, but excitement is exactly when people are most likely to overlook the boring bits. If the paperwork, the property and the planning position do not all tell the same story, find out why before you commit.
A few extra questions at the beginning can save a very expensive problem later.
For consultations, guides and further information:
www.benheathspain.com
Contact:
Web: www.benheathspain.com
Tel: +34 865 583 663








€50.000 to help purchase first home
Spain could let first-time buyers finance 100% of a home worth up to €250,000
The public financing will carry zero interest and no commissions. Photo credit: Manuel Milan/Shutterstock
If you have spent years watching house prices climb while your savings account refuses to keep up, buying your first home can feel like a game you cannot even start. You may be able to afford the monthly mortgage payments, but finding tens of thousands of euros for the deposit is a very different problem.
That is the barrier Spain’s government is now trying to tackle with a new financing scheme for first-time buyers. The plan could allow some people who have managed to save little or nothing for a deposit to finance the full value of a home, with properties costing up to around €250,000 potentially falling within the numbers. But there is an important catch: the scheme has been created, while the detailed rules for who will qualify and exactly how it will operate have not yet been finalised.
A €50,000 boost for first-time buyers
The new TU CASA mechanism has been created under a Royal Decree-Law published in Spain’s Official State Gazette on September 30 and entering into force on October 1. It is designed for people buying their first habitual home with a mortgage who can afford the repayments but do not have enough savings to cover the usual deposit. Under the legislation, the public loan can cover the lower of 20 per cent of the property’s value or €50,000. It will be managed by the Instituto de Crédito Oficial (ICO) and will be provided at 0 per cent interest with no commissions.
The government describes it as complementary financing, meaning it is not intended to replace the mortgage provided by a bank. That is where the much-discussed €250,000 figure comes from. If a bank provides an 80 per cent mortgage on a €250,000 home, that would amount to €200,000. The TU CASA loan could potentially provide the remaining €50,000, bringing the combined financing to the full €250,000 purchase price. It does not, however, mean that everyone without savings will automatically be able to buy a €250,000 property with no money upfront.
The rules are not all in place yet
The Royal Decree-Law establishes the financing mechanism, but it does not contain the complete set of eligibility conditions. A subsequent Council of Ministers agreement must establish the objectives, beneficiaries, limits, characteristics and initial amount of the financing line, as well as the application procedure. That means prospective buyers should not yet assume that simply having no savings and wanting to buy a first home will be enough.
The government has said the mechanism is aimed at people who can meet the cost of a mortgage but lack the savings normally required to get through the door in the first place. The legislation also makes clear that the property purchased through TU CASA will remain subject to a maximum resale price. In other words, this is not intended to be a way of buying a subsidised property and immediately selling it at whatever price the market will bear.
The public loan does not come with a normal mortgage bill
There is another significant difference between TU CASA and an ordinary bank loan. The public financing will carry zero interest and no commissions, with a repayment period of up to ten years. However, buyers will receive a period of grace linked to the mortgage, lasting until the mortgage is paid off or for a maximum of 30 years under the mechanism established in the decree.
The exact repayment arrangements will therefore depend on the final rules governing the scheme. The government says the measure is intended to help people who are capable of paying for a home but have been blocked by the upfront capital required to obtain a mortgage.
It will not make buying a home completely free
There is another detail prospective buyers should keep firmly in mind. Financing the purchase price does not necessarily mean having no costs whatsoever when buying a property. Depending on the type of home and where it is located, buyers can still face taxes, notary costs, registration fees and other expenses connected with the purchase.
The new public loan is designed to address the financing gap for the property itself, not wipe out every expense associated with becoming a homeowner. And the bank providing the mortgage will still have its own lending criteria. A buyer will therefore need to qualify for the private mortgage as well as meeting the eventual requirements for TU CASA.
When can buyers actually apply?
The Royal Decree-Law is already in force, but the practical details of the scheme are still being developed. The government says the Council of Ministers must now establish the detailed framework, including who can benefit and the limits that will apply. There is also a political step still to come: because this is a Royal Decree-Law, it must be convalidated by Congress.
For someone struggling to build a deposit while house prices continue to sit out of reach, that means the announcement is significant, but it is not yet a green light to walk into a bank and ask for the €50,000. What it does provide is a new route for first-time buyers who can afford the monthly cost of owning a home but have been stopped by the biggest hurdle at the beginning: finding the money to get the mortgage in the first place.

La Segunda Jornada Del Foro CREO, En Directo | Pablo Bustinduy Reclama “una Reforma Fiscal Justa” Y Subir Los Salarios

F1 urged to move Las Vegas Grand Prix over Antonelli title fears

Spain’s New 400 Phone Rule Starts Saturday


-

 Uncategorized2 weeks ago
F1 Bahrain Grand Prix will be live and FREE on TV this weekend
-
Blackout preparedness2 weeks ago
Brussels takes action against Spain over failure to update blackout plan
-
 Foreign demand3 weeks ago
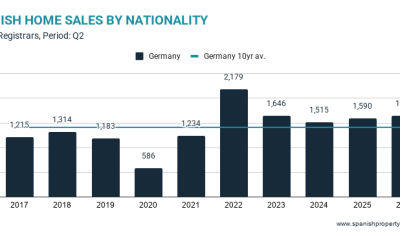
Market Snapshot: German Market In Q2 2026
-
 Uncategorized2 weeks ago
Lewis Hamilton F1 wish could come true as stunning plans for new track revealed
-
Latest2 weeks ago
Spain’s Government Dealt Huge Blow As MPs Reject Housing Crisis Laws
-
 Housing access / crisis / affordability2 weeks ago
Radical Housing Decrees Defeated As Snap Election Talk Grows
-
 New Developments2 weeks ago
How To Get A Tourist Rental Licence In Andalusia (Spain) – Step-By-Step Guide 2025
-
EU2 weeks ago
EU nicotine crackdown sparks warning that ex-smokers could be driven back to cigarettes